Expectancy
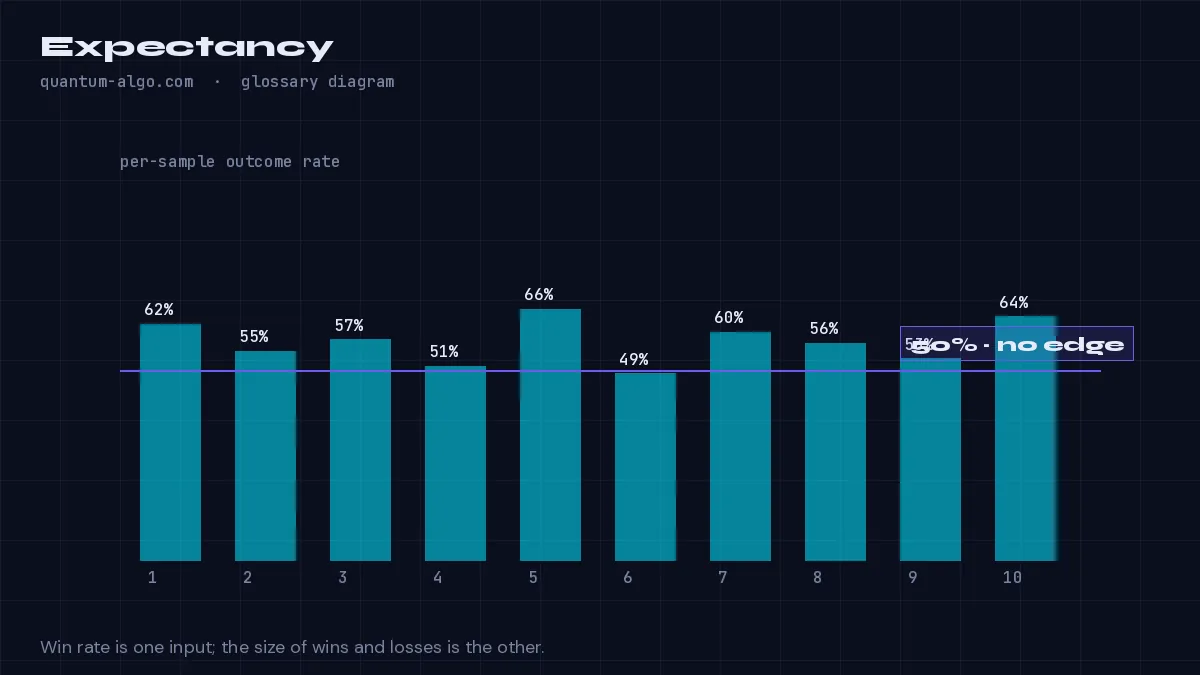
Expectancy is the average amount a strategy makes or loses per trade, in R or currency: (win rate × average win) − (loss rate × average loss); a positive expectancy is the definition of an edge, regardless of win rate.
What it means
Expectancy turns a track record into one number. If a system wins 40% of trades at +2R and loses 60% at −1R, expectancy is 0.4 × 2 − 0.6 × 1 = +0.2R per trade — profitable despite losing more often than it wins. A system winning 70% at +0.5R and losing 30% at −2R has expectancy −0.25R — a loser despite the flattering win rate.
It is the reason win rate alone means nothing and why every serious record reports reward-to-risk beside it. Quantum Algo's posted trades — 160 trades, 120 wins, 40 losses at an average 2.3:1 — express the same idea in public.
Expectancy needs a sample to be meaningful and is subject to the same small-sample problems as win rate; use it with a sample count and, ideally, a confidence bound.
How to identify it on a chart
- Log every trade's outcome in R (profit divided by initial risk).
- Compute win rate, average winning R and average losing R.
- Expectancy = win rate × average win − loss rate × average loss.
Worked example
Over 50 trades: 30 wins averaging +1.8R, 20 losses averaging −1R. Expectancy = 0.6 × 1.8 − 0.4 × 1 = +0.68R per trade; at 1% risk per trade that is +0.68% of the account per trade on average.
See it on the chart, read it in depth
Frequently asked questions
Can a strategy with a 35% win rate be profitable?
Yes, if winners are large enough: at 35% and 3:1 reward-to-risk, expectancy is 0.35 × 3 − 0.65 × 1 = +0.4R.
What is a good expectancy?
Anything reliably above zero after costs; +0.3R to +0.7R per trade is strong for discretionary systems.
How many trades before I trust it?
At least 50–100; check the win-rate component with a Wilson bound before believing the number.
Is expectancy the same as profit factor?
Related: profit factor is gross wins divided by gross losses; expectancy is the per-trade average. Both must be positive for an edge.
Related terms
See Expectancy on your TradingView chart
Zeno reads Smart Money structure across timeframes and prints the entry, stop and targets — with a public record of every posted trade. The free indicators draw the concepts this page defines.